
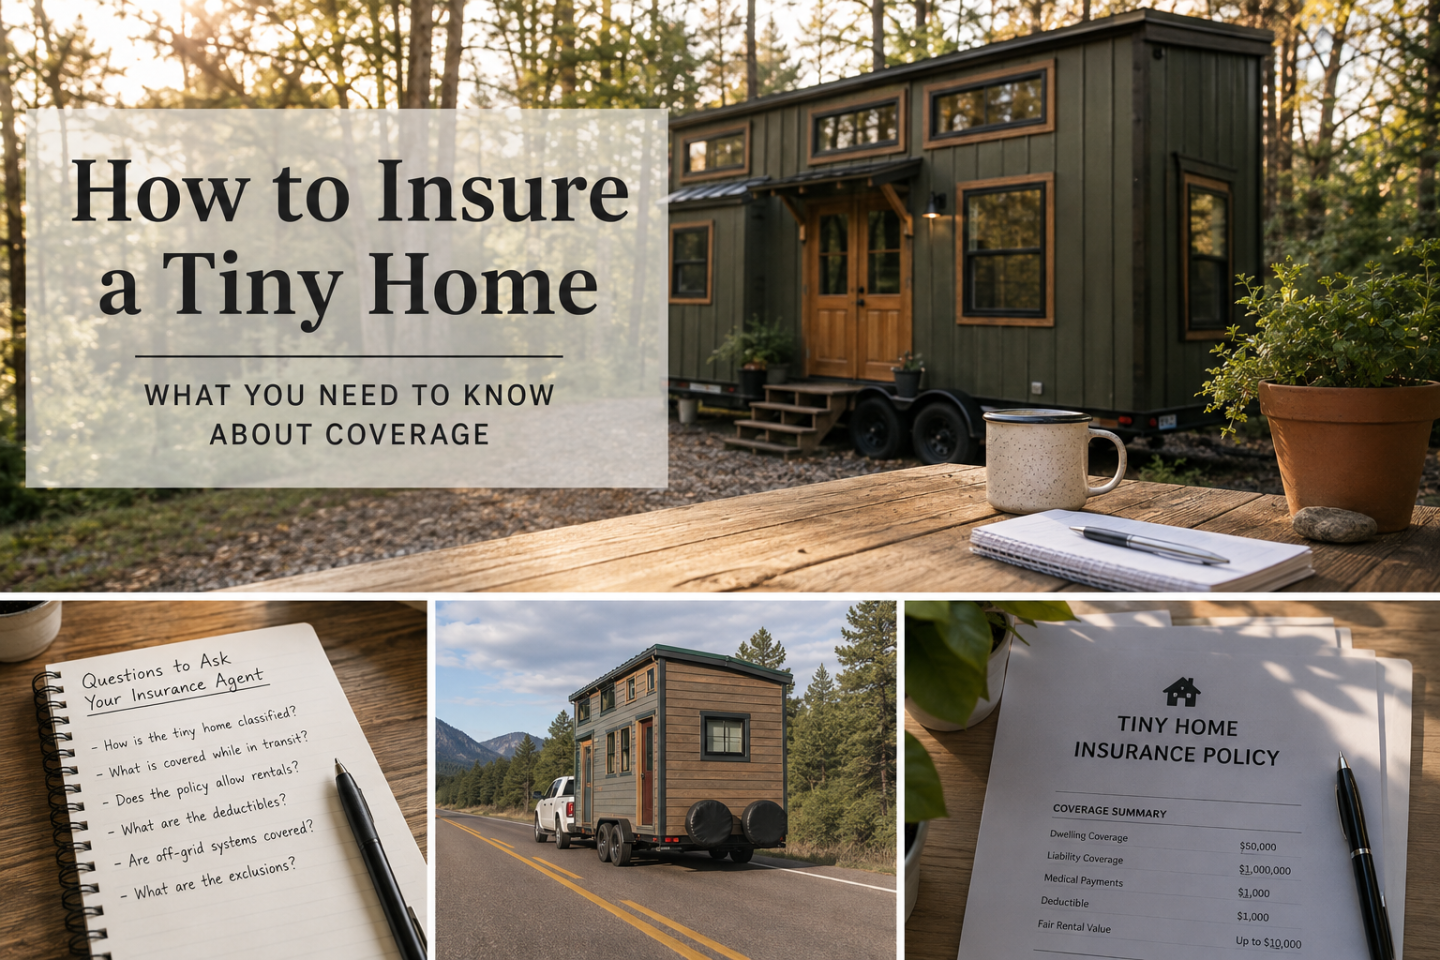
One of the biggest misconceptions about tiny homes is that because they’re smaller and usually less expensive than traditional houses, they must be easier to insure.
Unfortunately, that’s not always the case.
Tiny homes don’t fit neatly into the categories the insurance industry was built around. A tiny house might be considered a traditional dwelling, an RV, a park model, a rental property, or something else entirely depending on how it was built, whether it’s on wheels, where it’s parked, and how it’s being used.
That doesn’t mean tiny homes are impossible to insure. I know because I have insurance on my own tiny house. But finding the right coverage may require working with an agent who actually understands this unusual type of housing.
Why Can Tiny Homes Be Difficult to Insure?
Traditional homeowners insurance is designed around a fairly predictable property: a code-compliant house permanently attached to land.
Tiny homes can break a lot of those conventions.
A tiny house on wheels (THOW) can potentially be moved, making it different from a traditional dwelling. Some are built to RV standards, while others are DIY builds or have been inspected through third-party certification programs. Foundation-built tiny homes can have their own challenges, including minimum square footage requirements from certain insurers.
How you’re using the home matters, too.
A tiny house that’s your primary residence may need different coverage than one used as a vacation home or rental. And if it’s a short-term rental, that can introduce another set of considerations.
This is why I’d recommend researching insurance before purchasing a tiny home, not after.
My Own Tiny Home Insurance Policy
I personally insure my tiny home through Mac Insurance and worked with Michael Carmona to find coverage. Because I use my tiny house as a rental, my policy specifically identifies its use as “Rental.”
My current policy costs $900.22 per year, including taxes and fees. That’s about $75 per month.
Here’s a simplified look at some of my coverage:
- Dwelling coverage: $50,000
- Personal liability: $1 million
- Medical payments to others: $1,000
- Standard deductible: $1,000
- Theft coverage for contents: $1,000
- Use of tiny home: Rental
- Fair Rental Value coverage: Included for qualifying covered losses
It’s important to note that these are my specific policy limits, not an estimate of what another tiny homeowner will pay or receive. The cost of insurance can vary depending on the home’s value, location, construction, use, coverage limits, and other factors.
Rental Income Can Be Part of the Equation
One feature of my policy I find particularly interesting is Fair Rental Value coverage.
If a covered loss makes the rental unfit for normal use, the policy can cover its fair rental value, minus expenses that don’t continue while the property can’t be rented, for the shortest period required to repair or replace the affected portion.
My policy allows up to 20% of the dwelling coverage limit for Fair Rental Value and Additional Living Expense combined. With $50,000 in dwelling coverage, that’s potentially up to $10,000, subject to the policy’s terms and conditions.
For anyone using a tiny home to generate income, this is exactly the type of detail worth discussing with an insurance agent.
Short-Term Rentals Come With Important Fine Print
Here’s where reading the actual policy becomes especially important.
My policy contains a specific short-term rental endorsement. It defines a short-term rental as a rental period of less than six months with a lease agreement.
While the property is being used as a short-term rental, the deductible for most perils increases from my normal $1,000 deductible to $5,000. The endorsement also contains additional limitations involving vandalism and damage caused by burglars during short-term rentals.
That’s a pretty significant difference—and a perfect example of why simply asking, “Is my tiny house insured?” isn’t enough.
You need to ask how it’s insured and under what circumstances.
What About Moving a Tiny House?
Mobility is another reason tiny houses on wheels are different from conventional homes.
My policy paperwork includes endorsements for both Trip Collision Coverage and Theft of Tiny Home.
If you own a THOW, these are exactly the kinds of issues you should bring up with an agent. Don’t assume that a policy covering your house while it’s parked automatically provides the same protection while it’s being transported.
Ask specifically what happens if the tiny house is damaged while moving, stolen, or involved in an accident.
Understand What Isn’t Covered, Too
Insurance is just as much about exclusions as coverage.
For example, the base language of my policy excludes flooding, surface water, storm surge, sewer or drain backup, and certain forms of groundwater. Earth movement, including earthquakes and landslides, is also excluded under the general exclusions.
That doesn’t necessarily mean separate coverage can’t be purchased. It means homeowners shouldn’t assume every disaster is automatically covered under their tiny home policy.
The policy also doesn’t insure the land underneath the tiny house.
Again, this illustrates why tiny homeowners need to understand exactly what they’re purchasing.
Find an Agent Who Understands Tiny Homes
Perhaps the biggest lesson from my own experience is the value of working with someone familiar with tiny houses.
I’ve worked with Michael Carmona at Mac Insurance, and having an agent who understands alternative housing removes a lot of the confusion around explaining what the property is, how it’s built, and how it’s being used.
When you’re shopping for coverage, ask questions specific to your situation: Is the tiny home your primary residence or a rental? Is it on wheels? Will you ever move it? Is it professionally built or DIY? What certifications does it have? What happens if it’s stolen? Are your belongings covered? What is the deductible? And if you’re generating rental income, what happens if a covered loss makes the property temporarily uninhabitable?
Tiny home insurance is absolutely possible. But just like financing and zoning, tiny homes don’t always fit neatly into the systems created for conventional houses.
Finding someone who understands those differences—and reading the fine print—can make all the difference.
Discover more from Tiny House Giant Journey
Subscribe to get the latest posts sent to your email.

